
Gold and silver miner Polymetal decided to sell Russia assets
- September 22, 2023
- Posted by: Quatro Strategies
- Categories: Europe, Mining & Metals, Sanctions & Regulation
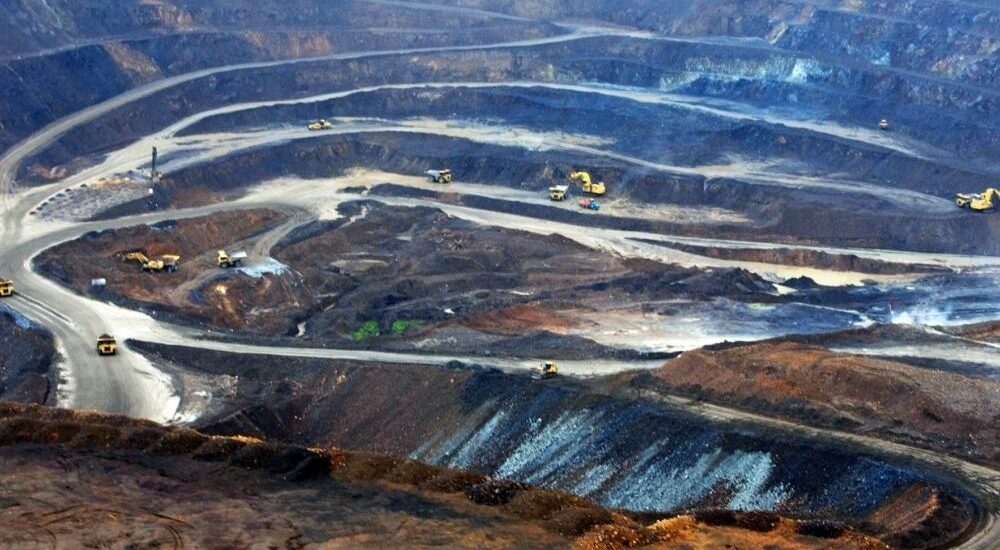
Polymetal International, a prominent gold and silver producer, has unveiled its intention to sell all of its Russian assets as a unified entity, rather than opting for a split, according to CEO Vitaly Nesis. This decision comes in the wake of sanctions imposed by the United States on Polymetal’s Russian business and Polyus, the largest gold producers in Russia, in response to Russia’s actions in Ukraine.
The move to sell the entire Russian business as a cohesive entity is aimed at preserving shareholder value, as fragmenting the assets through piecemeal sales could potentially erode value significantly.
Polymetal International had recently completed its re-domiciliation to Kazakhstan from Jersey, securing a listing on the Astana International Exchange (AIX) and committing to sell the Russian business within nine months.
Nesis addressed concerns related to Russia’s rule compelling investors from “unfriendly” jurisdictions to sell assets at half their market price, stating that this rule wouldn’t apply to Polymetal due to its redomiciliation to Kazakhstan. Additionally, he affirmed that the sale would not be to an entity on the US sanctions list, effectively ruling out Polyus as a potential buyer.
While potential buyers were not named and discussions have yet to commence, Nesis emphasized that the sale would not be a hurried process, aiming to secure a sale at a substantial value for the asset.
By QUATRO Strategies International Inc.
QUATRO Strategies International Inc. is the leading business insights and corporate strategy company based in Toronto, Ontario. Through our unique services, we counsel our clients on their key strategic issues, leveraging our deep industry expertise and using analytical rigor to help them make informed decisions to establish a competitive edge in the marketplace.
Interested in learning more?
Sign up for Top Insights Today
Top Insights Today delivers the latest insights straight to your inbox.
You will get daily industry insights on
Oil & Gas, Rare Earths & Commodities, Mining & Metals, EVs & Battery Technology, ESG & Renewable Energy, AI & Semiconductors, Aerospace & Defense, Sanctions & Regulation, Business & Politics.
Read more insights
Beijing hoards helium as Gulf supply risks return
China’s temporary ban on helium exports is a defensive response to renewed conflict in the Middle East and the risk that disruptions to Qatari supply could leave Chinese semiconductor manufacturers without enough of a gas that is essential to advanced chip production. The restriction took effect immediately, indicating that Beijing is prioritizing domestic industrial continuity over the relatively small volumes of helium that Chinese companies normally sell to other Asian markets.
The decision is unusual because China is not a major net supplier of helium. It is heavily dependent on foreign sources, with imports estimated to cover about 85 percent of domestic requirements. Chinese companies export only limited surplus volumes when local availability exceeds immediate needs or when regional prices make overseas sales attractive.
China plots smelter ceilings to end ‘Involution’ after aluminium’s lesson
Beijing’s experience with aluminium shows how a hard, well-policed capacity ceiling can curb the worst excesses of China’s “build first, worry later” industrial cycle, and the country’s non-ferrous association now wants to port that playbook to copper, lead and zinc.
The problem they’re trying to solve is straightforward: smelting capacity has outrun the availability of raw materials. China’s refiners have lifted output rapidly, with copper metal production is up double digits year on year, but concentrates haven’t kept pace.
Global wind power growth to slow in 2024 amid rising costs and policy uncertainty
Global wind power growth is anticipated to decelerate this year due to various challenges such as escalating costs, inadequate infrastructure, and policy ambiguity. Installations are projected to increase by nearly 6% in 2024, a significant slowdown compared to the nearly 35% surge observed in 2023…