
Lloyd’s of London raising Taiwan rates as insurers acknowledge conflict risks
- August 20, 2023
- Posted by: Quatro Strategies
- Categories: China, Europe, Sanctions & Regulation
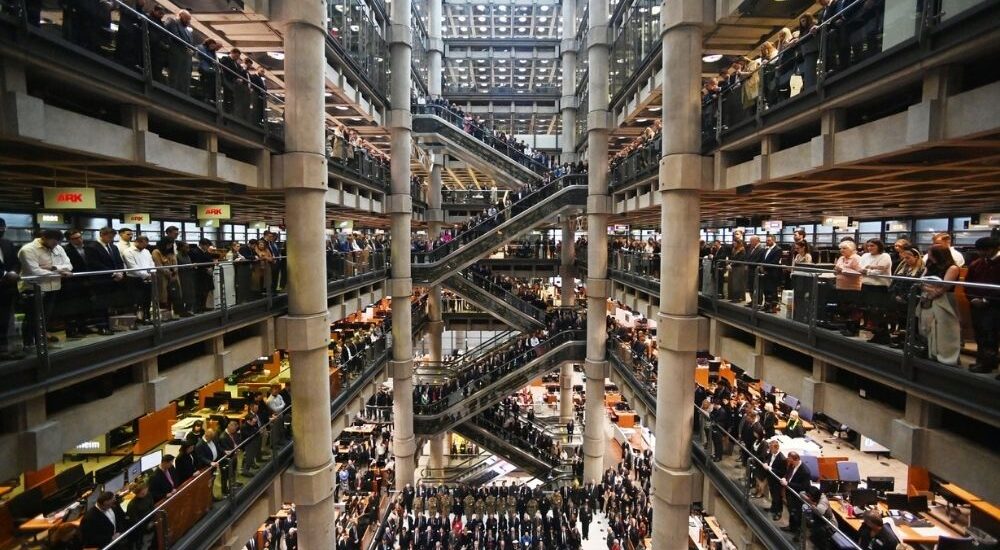
Lloyd’s of London underwriters, recognized as leaders in the insurance industry, are taking proactive measures to mitigate potential risks associated with Taiwan. They are reportedly increasing insurance rates and reducing the amount of coverage offered for risks related to Taiwan, as concerns over the possibility of military action by China continue to grow. This move follows a similar response by insurers after Russia’s unexpected invasion of Ukraine last year, which led to insurers excluding Russia and Ukraine from policies or imposing higher rates due to heightened geopolitical risks.
The decision to raise rates and limit coverage for Taiwan reflects the insurance industry’s cautious approach to geopolitical uncertainties and potential conflicts. The ongoing tensions between China and Taiwan have raised concerns about the potential disruption to global supply chains, particularly in the semiconductor industry, as Taiwan is a crucial player in advanced chip manufacturing. Any disruption to chip production in Taiwan could have far-reaching consequences for various industries, potentially impacting everything from electronics manufacturing to automotive production.
Taiwan’s significance in the global economy cannot be understated. The island nation is a major producer of advanced semiconductor chips, which are essential components in numerous electronic devices. U.S. Director of National Intelligence Avril Haines estimated that a Chinese invasion of Taiwan leading to the disruption of chip production could wipe out up to $1 trillion per year from the global economy, underscoring the potential magnitude of the impact.
The insurance industry’s response to the Taiwan situation highlights the broader ripple effects that geopolitical tensions and conflicts can have on various sectors and the economy as a whole. Insurers are taking preemptive steps to manage their exposure to potential losses caused by disruptions resulting from conflicts or geopolitical events. As geopolitical risks continue to evolve, insurers are seeking to strike a balance between providing coverage and managing their own financial stability.
One aspect of insurers’ concerns is the potential for damage or destruction of ships and aircraft in Taiwanese ports and airports in the event of a conflict. This not only affects insurers but also raises issues for businesses that rely on these assets for their operations. Moreover, some insurers are already imposing exclusions on Taiwan in political risk or political violence policies. These policies cover property damage and business interruption losses related to issues such as terrorism, sabotage, and war. This indicates a broader trend of insurers becoming more cautious about providing coverage for risks associated with Taiwan.
The insurance industry’s move to tighten coverage and raise rates for Taiwan underscores the complex interplay between global politics, economic stability, and the insurance sector’s risk assessment strategies. The world’s interconnectedness means that events in one part of the globe can have cascading effects across industries and regions. As such, insurers are keenly aware of the need to carefully evaluate and adjust their risk management approaches in response to evolving geopolitical uncertainties. This strategic approach aims to ensure that insurers are prepared to navigate potential challenges and provide stability in a world where geopolitical risks are an ever-present consideration.
Interested in learning more?
Sign up for Top Insights Today
Top Insights Today delivers the latest insights straight to your inbox.
You will get daily industry insights on
Oil & Gas, Rare Earths & Commodities, Mining & Metals, EVs & Battery Technology, ESG & Renewable Energy, AI & Semiconductors, Aerospace & Defense, Sanctions & Regulation, Business & Politics.
Read more insights
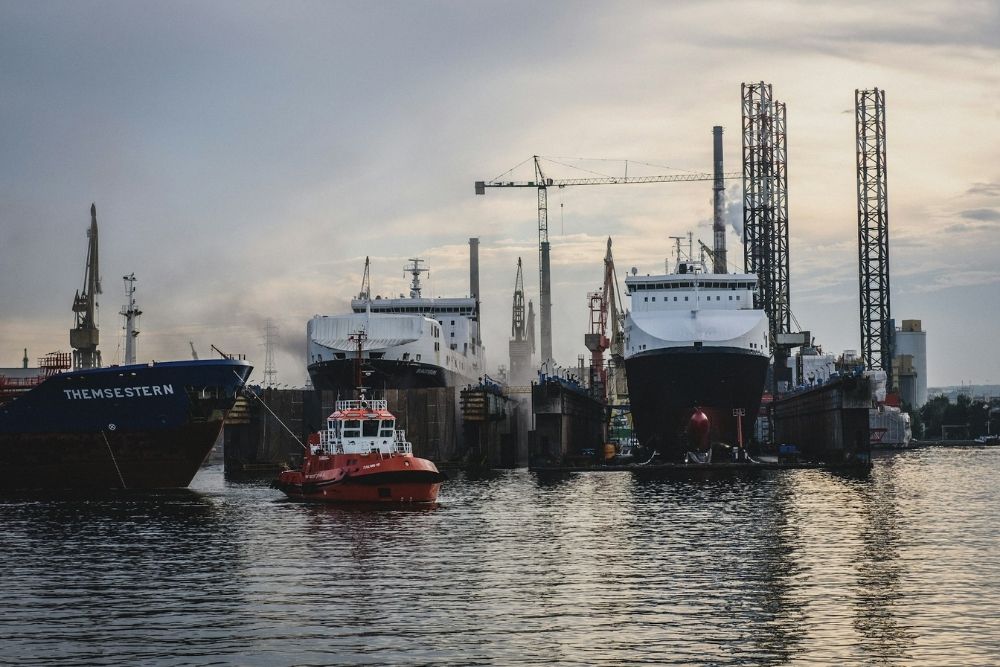
U.S. seeks to enlist South Korea in curbing China’s shipbuilding dominance
Washington’s move to tap Seoul as a strategic partner in countering China’s growing grip on global shipbuilding underscores how industrial policy is becoming an increasingly sharp tool in the geopolitical contest with Beijing. The comments from South Korea show that the U.S. is not merely focused on short-term trade concessions, but on forging longer-term coalitions to push back against China’s rise in key manufacturing sectors.
China overtook South Korea as the world’s top shipbuilder in the early 2010s, and now accounts for roughly 50% of global ship production by tonnage, compared with South Korea’s roughly 30%. China also dominates orders for certain vessel types, including bulk carriers and container ships, and is advancing quickly in LNG carrier technologies, a sector traditionally led by Korea.
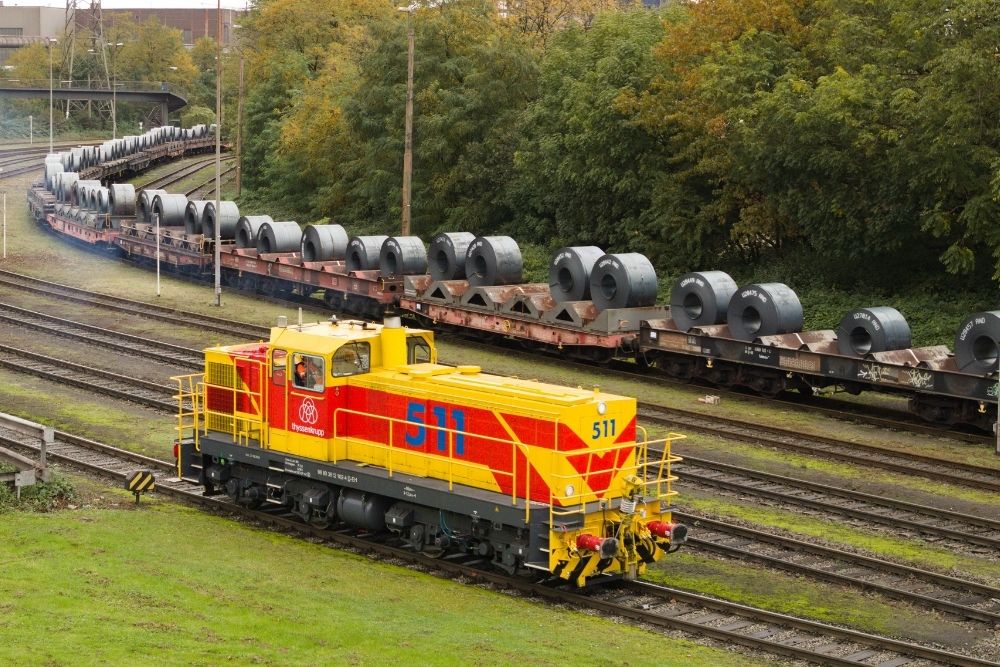
China’s steel output slumps to seven-year low but iron ore imports hit record
China’s steel sector is ending 2025 in a conspicuously weaker position than the bulk-commodity trade feeding it. Official November output data show crude steel production falling to about 69.9 million tons, down roughly 11% from a year earlier and the weakest month since late 2023, putting the country on track for its lowest full-year steel output since 2018.
Yet, at the same time, China’s iron ore imports, steelmaking’s principal feedstock, are poised to set a new record in 2025, surpassing the prior high reached in 2024.
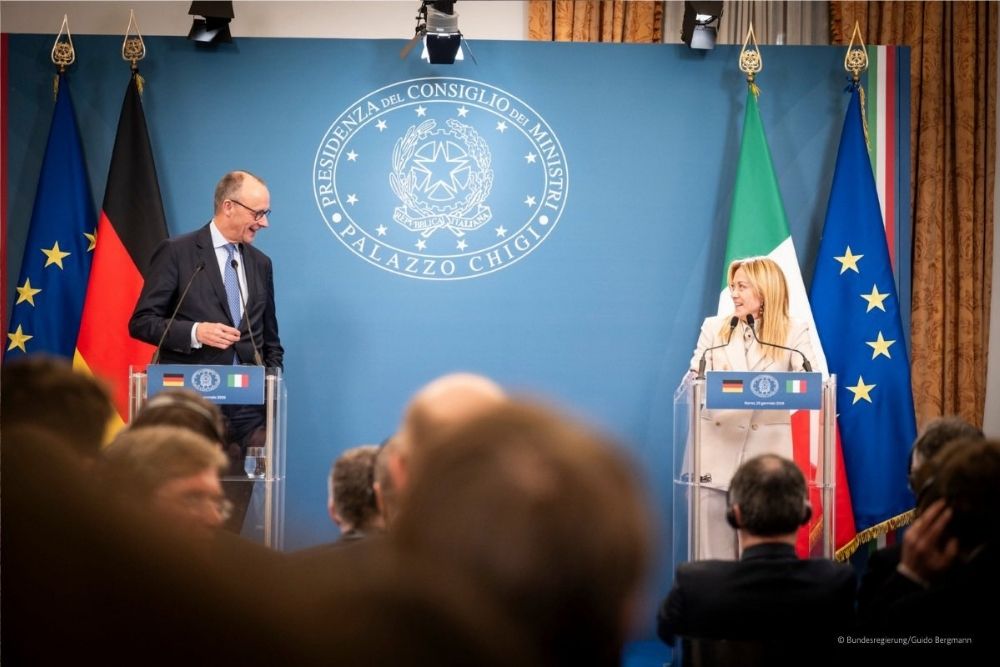
Italy, Germany push EU “economic security” line on raw materials
Italy and Germany are moving to formalize a joint “economic security” track around critical raw materials, framed explicitly as a response to China’s ability to influence prices and availability for inputs that sit upstream of European industrial competitiveness and defense readiness.
At the Rome intergovernmental summit, the two governments committed (in a draft document) to cooperate on securing supply chains for critical raw materials used across “strategic technologies and sector applications,” and to use that cooperation to strengthen coordination inside the EU as well as with transatlantic and other “like-minded” partners.