
British chipmaker Arm set for IPO despite industry woes
- August 22, 2023
- Posted by: Quatro Strategies
- Categories: AI & Semiconductors, Asia Pacific, Business & Politics, Europe
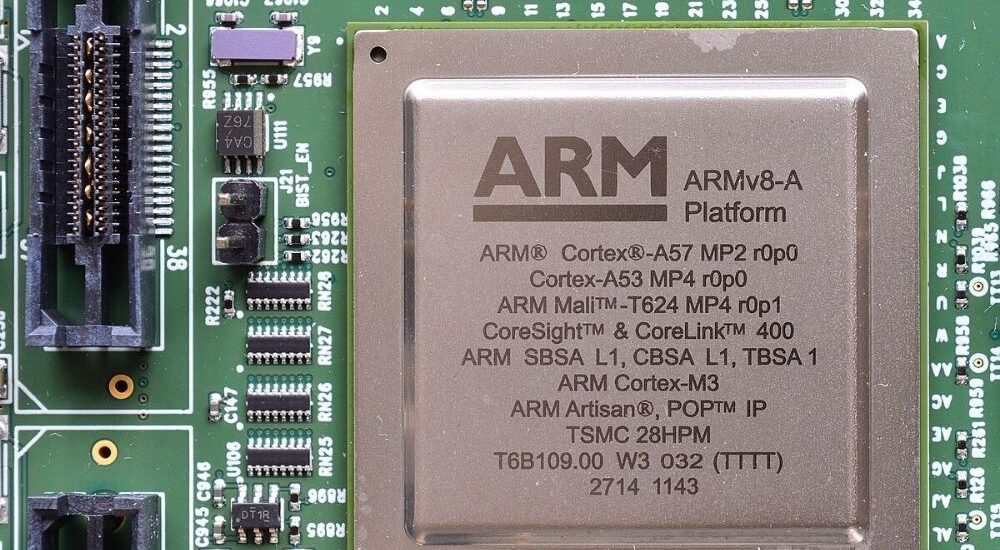
Arm Holdings, a leading chip designer, reported a 1% fall in annual revenue due to a slowdown in smartphone sales. The company’s annual sales for the year ended March 31 were $2.68 billion, primarily impacted by a decline in global smartphone shipments. Arm’s stock market launch is expected to be the largest IPO of the year and could revive the IPO market, which has seen volatility in recent times. Despite its reliance on smartphones for royalties, Arm’s relatively modest decline in revenue suggests that its per-chip rates have increased.
Arm Holdings’ chip technology powers most smartphones, including iPhones. The company did not reveal the number of shares it plans to sell or the valuation it is seeking for the IPO. SoftBank, Arm’s parent company, plans to sell about 10% of Arm’s shares in the IPO and is aiming for a valuation of between $60 billion and $70 billion for the chip designer.
Arm’s technology is widely used in smartphones, laptops, and servers, and it has also gained a 10% market share in cloud computing. The company’s chip designs are dominant in the smartphone industry, and it’s looking to expand into other segments such as cloud computing.
The IPO will be a boost to the market, and Arm is expected to list on the Nasdaq under the ticker symbol ‘ARM’. Barclays, Goldman Sachs, JPMorgan Chase, and Mizuho Financial Group are the lead underwriters for the offering. Arm Holdings is known for its chip design technology that is used in various electronic devices and has been a key player in the tech industry for several years.
Interested in learning more?
Sign up for Top Insights Today
Top Insights Today delivers the latest insights straight to your inbox.
You will get daily industry insights on
Oil & Gas, Rare Earths & Commodities, Mining & Metals, EVs & Battery Technology, ESG & Renewable Energy, AI & Semiconductors, Aerospace & Defense, Sanctions & Regulation, Business & Politics.
Read more insights
Europe’s transport majors face earnings squeeze as freight rates slide
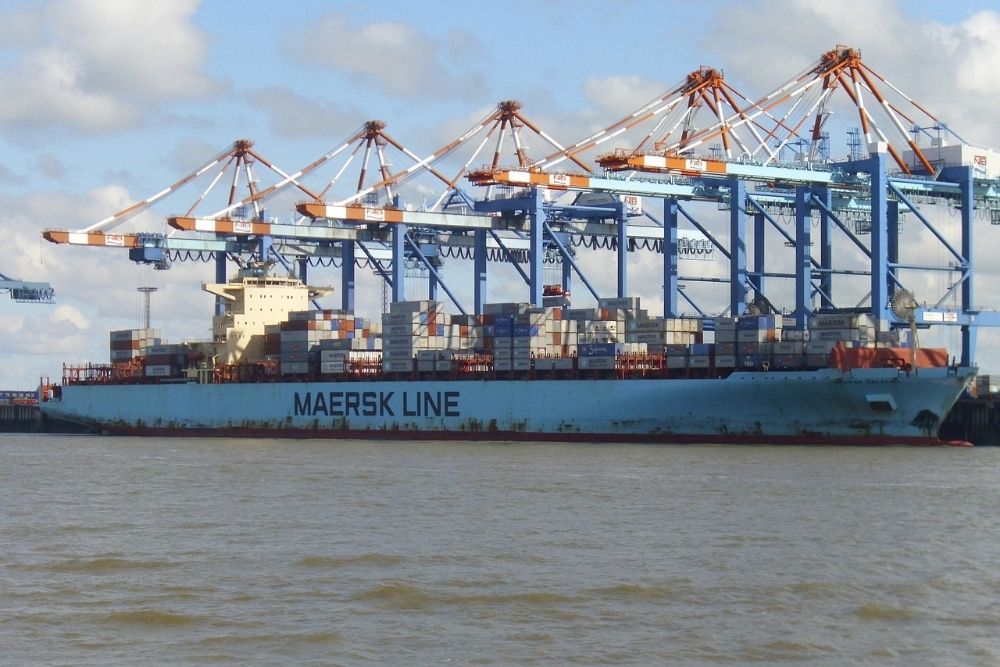
Europe’s transport bellwethers are sailing into earnings with the wind in their faces. After a brief spring rebound, container freight rates have slid back toward multi-year lows as too many ships chase too little cargo, and as new U.S. tariffs and trade frictions sap peak-season bookings that normally pad third-quarter results.
Forwarders are feeling it first in thinner sea and air yields; integrated parcel players are contending with softer express volumes and weaker premium surcharges. The one relative outlier remains Maersk, whose contract-heavy book cushions the immediate blow. When most of your liftings are priced off annual agreements negotiated when spot lanes still looked firmer, revenue lags the spot downturn.

Asia’s petrochemical squeeze is reaching everyday consumer goods
The Iran war is beginning to hit Asia not only through oil prices or headline shortages, but through the physical materials that sit inside everyday consumer goods. The disruption of Gulf energy and petrochemical flows is now feeding directly into the cost and availability of plastics, packaging, synthetic rubber and other petroleum-derived inputs used in products ranging from instant noodles and cosmetics to agricultural film, toys and snacks.
That is why the story matters: the shock is moving beyond refineries and into the mundane, mass-market goods that shape daily life across the region. The core mechanism is naphtha and petrochemicals. Asia depends heavily on Middle Eastern oil derivatives, and the Strait of Hormuz disruption has sharply tightened access to naphtha, a key feedstock for plastics and chemicals.
China considers solar tool export limits to the U.S.
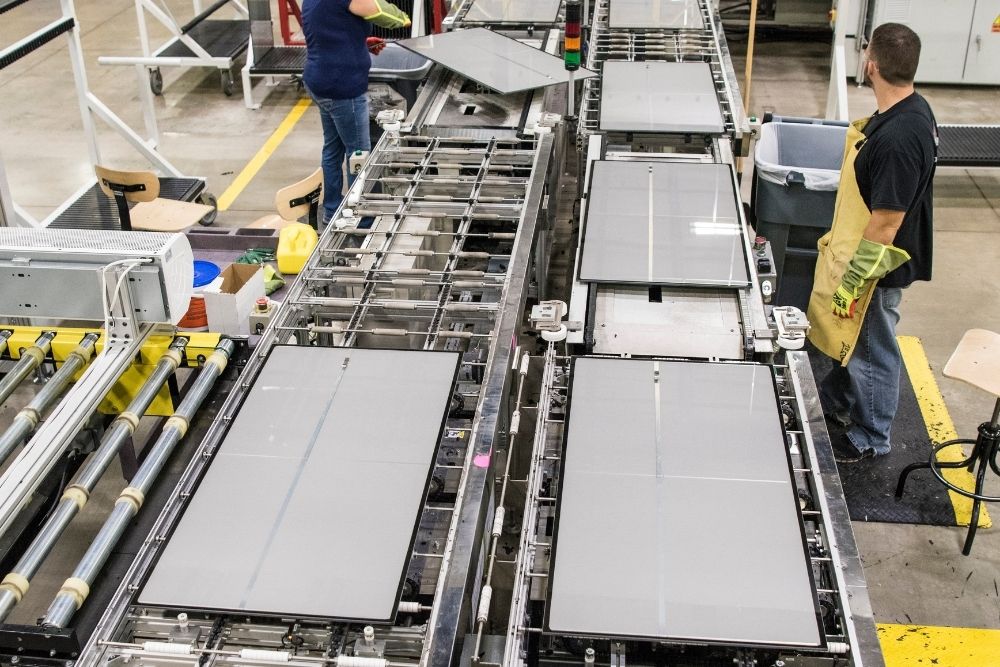
China is considering whether to restrict exports of advanced solar manufacturing equipment to the United States, a move that would mark a significant escalation in the clean-tech rivalry between the two countries. Officials have begun preliminary consultations with equipment suppliers, including discussions around higher-end tools used to make more efficient solar cells, but no final rule has been adopted and the process has not yet reached the stage of formal industry consultation.
The background is that China’s dominance in solar no longer rests only on low-cost panel production. It also extends deep into the manufacturing ecosystem itself. China produces more than 80% of the world’s solar panel components and is home to the top suppliers of the machinery used to make solar cells.