
Mining sector having difficulty meeting decarbonization targets
- September 11, 2023
- Posted by: Quatro Strategies
- Category: Mining & Metals
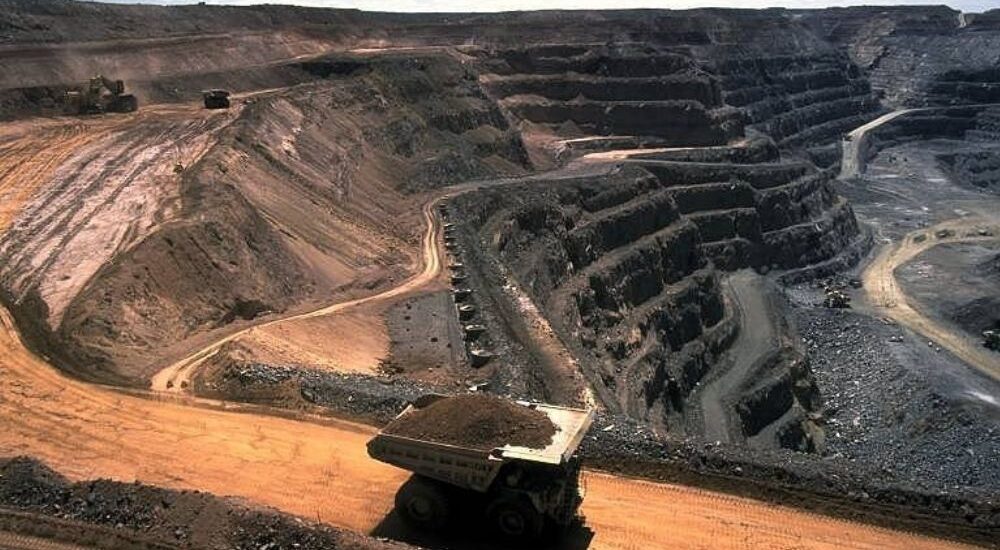
A lack of consistent and transparent data to measure emissions along the supply chain of mining companies is hindering efforts to monitor and meet decarbonization targets within the sector. Mining is a critical industry for supplying the raw materials needed for electric vehicles and renewable energy infrastructure, yet it also contributes to 4% to 7% of global greenhouse gas emissions.
The challenge lies in the complexity of the supply chain. Mining companies produce metals used in various industries, serving customers across different regions, making it difficult to track emissions across the entire value chain. This issue is further complicated by varying levels of transparency from suppliers.
To address this problem, the International Council on Mining and Metals (ICMM), which includes approximately 25 mining companies, has published guidance for mining companies on how to account for and report their Scope 3 emissions. Scope 3 emissions are indirect emissions, such as those originating from third-party suppliers. This guidance aims to create a consistent reporting framework and help companies better account for their emissions.
Many mining companies have set decarbonization targets with the goal of achieving net-zero emissions by 2040 or 2050. However, some are facing challenges in meeting these targets. For example, Rio Tinto, the world’s second-largest mining company, announced in July that it might miss its 2025 target unless it resorts to purchasing carbon offsets.
Investors are increasingly looking for mining companies to align their targets with net-zero goals across all scopes of emissions (Scope 1, 2, and 3) and to set clear short, medium, and long-term targets to demonstrate their commitment to reducing emissions. The challenge for the mining industry lies in ensuring the entire supply chain adheres to these goals, as emissions reductions depend on actions taken by suppliers and partners throughout the value chain.
Interested in learning more?
Sign up for Top Insights Today
Top Insights Today delivers the latest insights straight to your inbox.
You will get daily industry insights on
Oil & Gas, Rare Earths & Commodities, Mining & Metals, EVs & Battery Technology, ESG & Renewable Energy, AI & Semiconductors, Aerospace & Defense, Sanctions & Regulation, Business & Politics.
Read more insights

US redirects Zambia funding toward Lobito minerals infrastructure
Zambia has agreed with the US Millennium Challenge Corporation to expand the use of a 491-million-dollar agriculture grant to support critical minerals infrastructure, redirecting funds originally intended for agricultural development toward the Lobito Corridor that has become central to the Western effort to secure African critical minerals and counter Chinese dominance.
The realignment of the grant, which will support both Zambia’s agricultural and critical minerals economy along the corridor, illustrates the growing strategic priority that critical minerals have assumed in American engagement with Africa and the integration of infrastructure development into the broader competition for the materials essential to the energy transition.

Europe’s carmakers are using nostalgia to make EVs feel familiar
European carmakers are turning familiar models into a way of making electric vehicles feel less unfamiliar. Reviving names such as the Renault 5 and Citroën 2CV allows manufacturers to connect new technology with memories of family cars, first journeys and everyday independence.
As Chinese competitors challenge them on price and technology, that emotional connection offers another reason for customers to choose a European brand. Its commercial value will depend on whether the revived cars deliver the affordability and usefulness that made their predecessors successful.
China’s NCM precursors move to shrink cobalt discounts
China’s nickel-manganese-cobalt (NCM) battery supply chain is testing its first meaningful pricing power in nearly two years. Precursor producers, the firms that blend nickel, manganese, and cobalt into the feedstock used for NCM cathodes, are pushing to narrow the traditional discount they grant to spot cobalt sulfate, moving from roughly 10% toward 5% on long-term contracts and signaling tighter terms on spot volumes next year.
The timing is no accident. Cobalt prices have more than doubled this year after the Democratic Republic of the Congo, the dominant producer, imposed export restrictions, lifting the metal from about $10 per pound in late February to roughly $24. That rally has broken a three-year slump and, paired with early signs of a demand uptick in China’s battery market, has emboldened upstream suppliers to reclaim margin they surrendered during the downcycle.