
Saudi Arabia, Russia agree to extend oil output cuts until the end of 2023
- September 6, 2023
- Posted by: Quatro Strategies
- Categories: Europe, Middle East, Oil & Gas, Sanctions & Regulation
Saudi Arabia and Russia have jointly announced that they will extend voluntary oil production cuts until the end of the year. This decision, which came as a surprise to many in the oil market, will keep approximately 1.3 million barrels per day off the global market. Despite rising oil prices and expectations of tight supply in the fourth quarter, the two major oil-producing nations have chosen to maintain these cuts.
The news of the extension caused oil prices to rise, with Brent crude surpassing $90 per barrel for the first time since November. This decision is seen as a setback for U.S. President Joe Biden, who has been urging OPEC+ (the alliance of OPEC and non-OPEC oil-producing countries led by Russia) to increase production to lower energy costs and support the global economy.
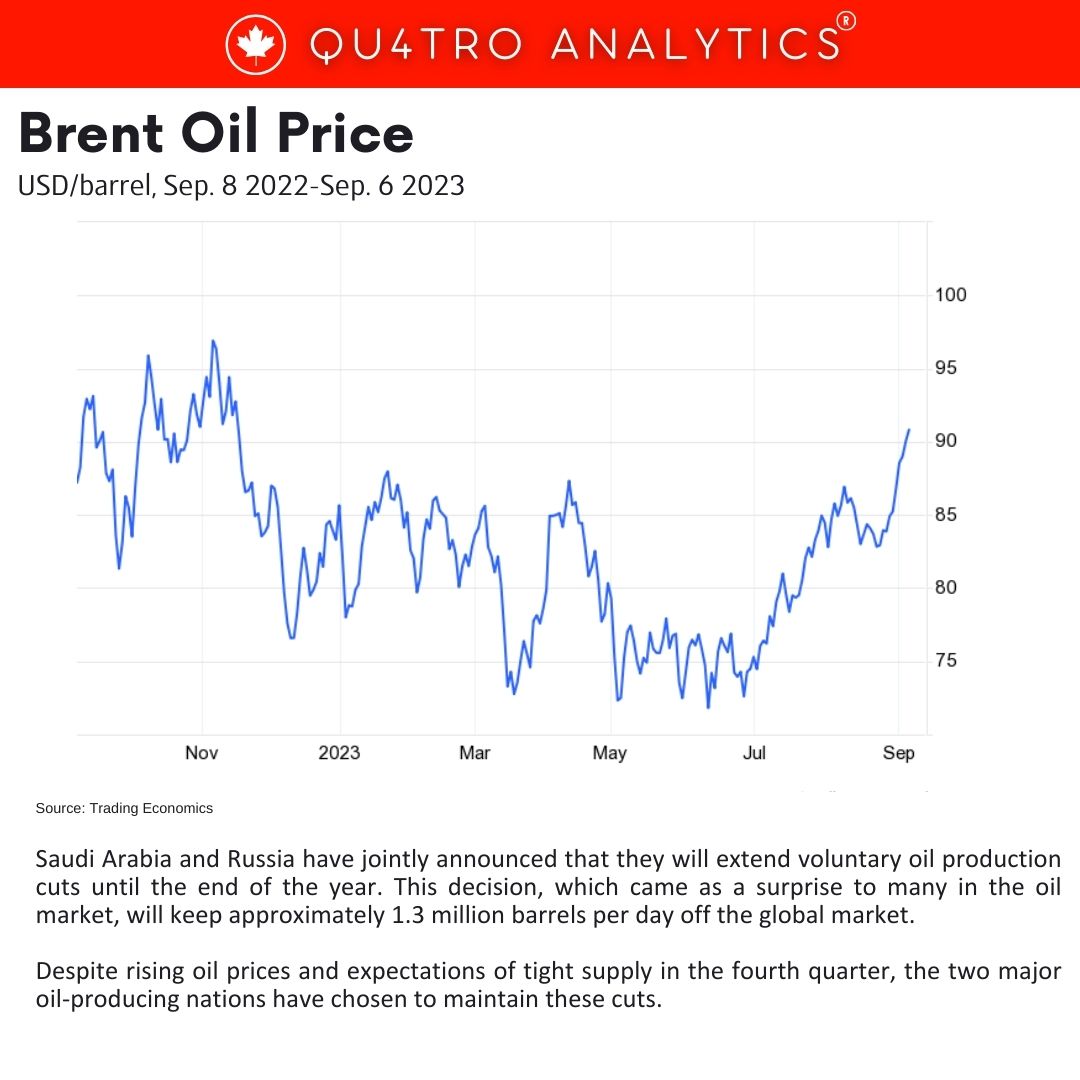 Saudi Arabia will continue its voluntary oil output cut of 1 million barrels per day (bpd) for an additional three months, extending until the end of December 2023. Russia, on the other hand, will extend its voluntary reduction of oil exports by 300,000 bpd until the end of this year. Both countries have stated that they will review these cut decisions on a monthly basis, considering adjustments based on market conditions.
These voluntary production cuts are in addition to the April cut agreed upon by several OPEC+ producers, which is set to extend until the end of 2024. While Saudi Arabia and Russia have cited market stability as their reason for these cuts, they have also expressed concerns about the value of their oil exports being impacted by Western central bank policies, which have included extensive money printing.
For Saudi Arabia and Russia, these cuts serve both economic and geopolitical purposes. They help to keep oil prices elevated, providing more revenue to their respective governments. Additionally, the move allows them to maintain a degree of influence in global oil markets, particularly at a time when geopolitical tensions, such as Russia’s war in Ukraine, are affecting the energy landscape.
Interested in learning more?
Sign up for Top Insights Today
Top Insights Today delivers the latest insights straight to your inbox.
You will get daily industry insights on
Oil & Gas, Rare Earths & Commodities, Mining & Metals, EVs & Battery Technology, ESG & Renewable Energy, AI & Semiconductors, Aerospace & Defense, Sanctions & Regulation, Business & Politics.
Read more insights
Debt service becomes the West’s binding strategic constraint
There is a category of statistic that reveals more about a country’s future than any strategy document. Every G7 member except Germany and Canada now spends more servicing its debt than defending itself. At a moment when the West has committed to the largest rearmament programme since the Cold War, with a war in the Persian Gulf entering its sixth month and NATO targets rising toward 5 percent of GDP, the bond market is already collecting a larger share of the public purse than the armed forces.
That is not a temporary imbalance. It is the constraint within which every strategic ambition of the next decade must fit. The country breakdown gives the finding its edge. Interest costs this year will amount to 193 percent of defence spending in Italy, 121 percent in the United States, 105 percent in the United Kingdom and 103 percent in France, against just 35 percent in Germany.
Markets question U.S. haven status amid Greenland tariff standoff
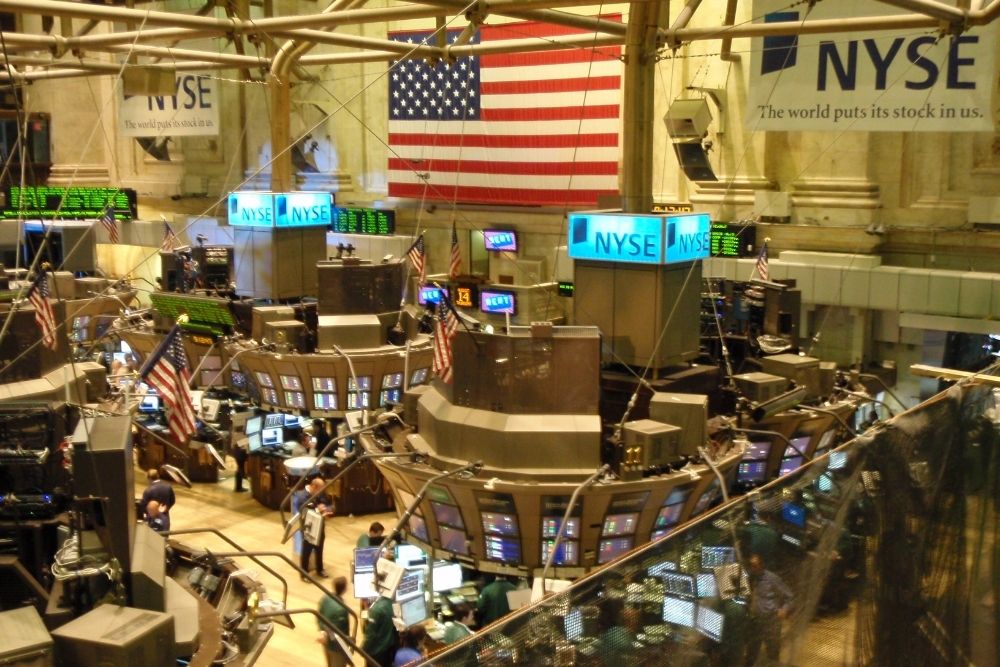
Markets are relearning an old lesson about the Trump era: volatility is not just a function of economic data, but of political optionality. As President Donald Trump begins the second year of his second term, the trade-and-geopolitics complex that has repeatedly jolted risk sentiment is back in the foreground, and the initial market response suggests investors are less willing to reflexively “buy the dip” than they were after last year’s tariff shocks.
The immediate trigger was Trump’s escalation of tariff threats against European allies in connection with his push to control Greenland, an issue that markets read not merely as a trade dispute, but as a stress test of the transatlantic security architecture.
U.S.-India trade framework ties tariffs to Russia oil compliance
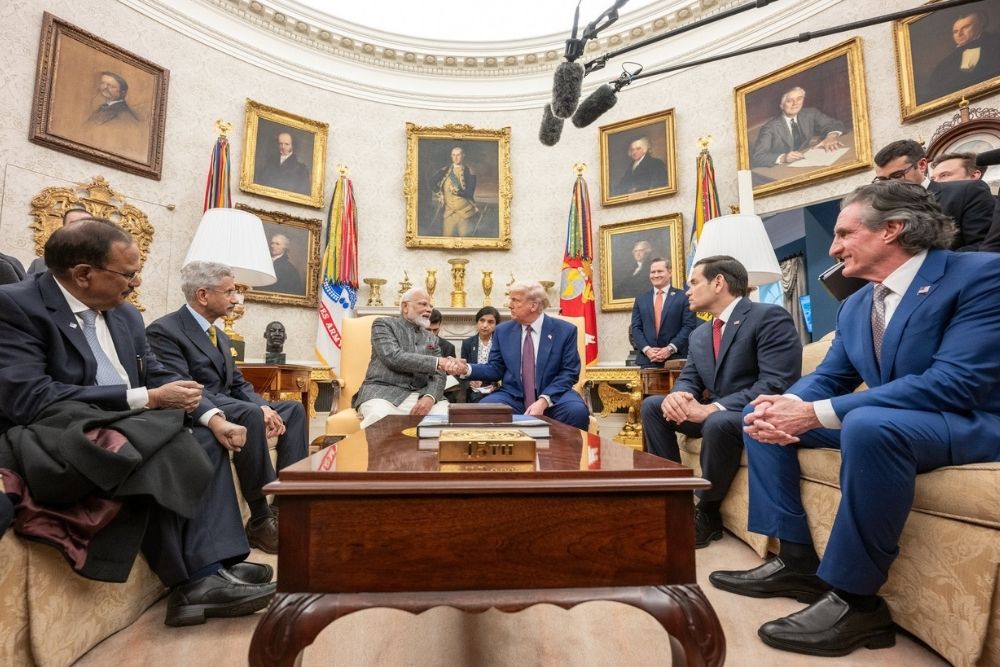
The interim U.S.-India trade framework released Friday is best read as a strategic bargain dressed as a tariff deal: Washington is trading improved market access and a lower headline U.S. tariff rate for Indian goods for two things it values more than incremental commerce: energy realignment away from Russia and a tighter alignment with U.S. preferences on standards, sensitive technology controls, and China-related “non-market” concerns.
The agreement is a framework rather than a finished treaty, but it is detailed enough to show the direction of travel: India lowers barriers across a wide swath of U.S. industrial and selected farm inputs, the United States keeps a still-material 18% tariff on most Indian imports, and both sides tie the relationship to supply-chain restructuring and economic security.