Vietnam expects delays in offshore gas projects, putting its power supply at risk
- October 5, 2023
- Posted by: Quatro Strategies
- Categories: Asia Pacific, Oil & Gas
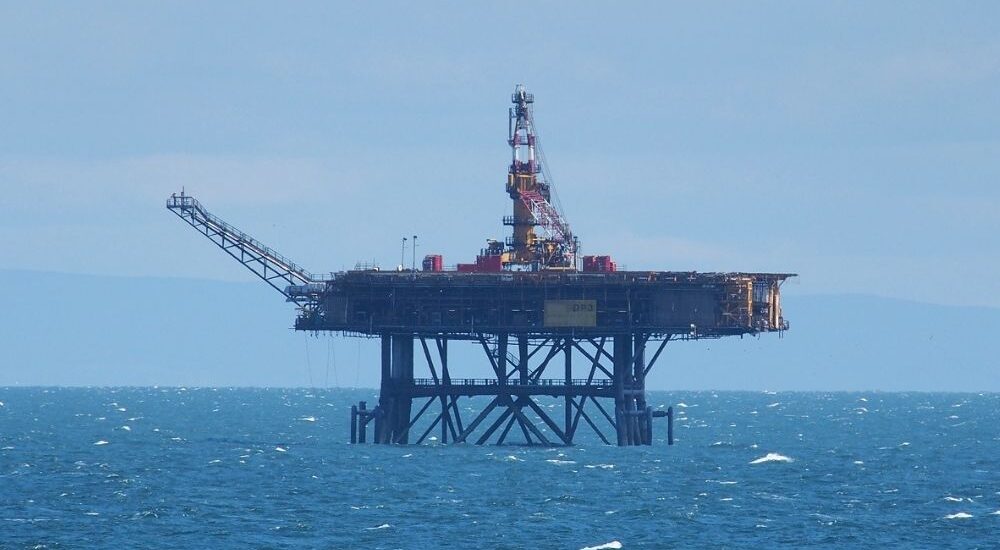
Vietnam’s offshore gas development projects involving major players like Exxon Mobil and Gazprom are facing significant delays, as per a draft government document. This situation raises concerns about the future of these projects in the South China Sea, where Vietnam and China have territorial disputes. Particularly, Exxon has been exploring options to withdraw from its Blue Whale project off Vietnam’s coast due to increasing pressure to align with green-energy goals.
Delays in these projects could also add to Vietnam’s ongoing concerns about its power supply. The country has experienced blackouts in recent months and planned to rely on domestic gas, including gas from Exxon and Gazprom projects, for a significant portion of its power generation capacity by 2030. The Blue Whale project, for example, was designed to consist of five power plants with a combined capacity of almost 4 gigawatts, but none of these plants have been built yet.
The draft document from Vietnam’s industry ministry, dated August 31, suggested a new timeline for the Blue Whale project, indicating that the five power plants will become operational when gas is available from that block, tentatively in 2028. It also noted that gas sale agreements for four of these plants are expected to be signed this year.
Exxon has been actively seeking buyers for the Blue Whale project for years. While Exxon states that business activities for the project are continuing as usual, there’s growing uncertainty about the future of the project. Administrative hurdles and disagreements over electricity pricing with Vietnam’s power grid operator have contributed to delays in the project’s development.
Similarly, Gazprom’s main gas project in Vietnam is also facing prolonged uncertainty. The government draft document suggests that Gazprom’s plant, which was initially expected to be operational before the end of this decade, is now unlikely to come online before 2030 as the company is assessing gas reserves.
These delays in major offshore gas projects may impact Vietnam’s ability to secure its power supply and meet its energy goals. Moreover, the territorial disputes in the South China Sea further complicate the situation, adding geopolitical dimensions to the challenges faced by these projects.
QUATRO Strategies International Inc. is the leading business insights and corporate strategy company based in Toronto, Ontario. Through our unique services, we counsel our clients on their key strategic issues, leveraging our deep industry expertise and using analytical rigor to help them make informed decisions to establish a competitive edge in the marketplace.
Interested in learning more?
Sign up for Top Insights Today
Top Insights Today delivers the latest insights straight to your inbox.
You will get daily industry insights on
Oil & Gas, Rare Earths & Commodities, Mining & Metals, EVs & Battery Technology, ESG & Renewable Energy, AI & Semiconductors, Aerospace & Defense, Sanctions & Regulation, Business & Politics.
Read more insights
Brussels’ local-content turn threatens UK role in green industrial chains
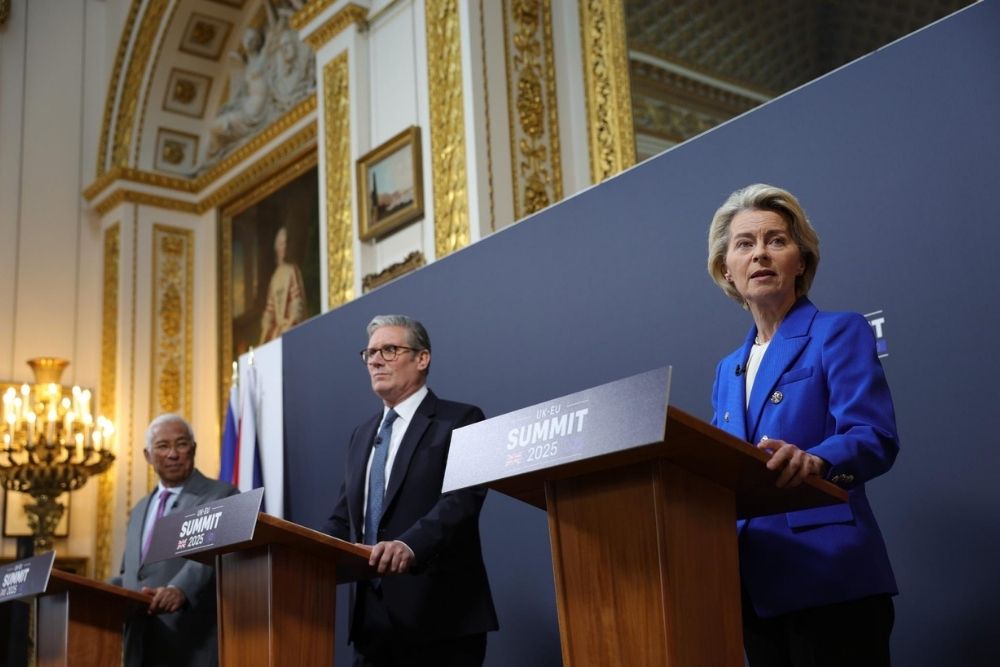
The UK government is increasingly worried that the EU’s emerging “Made in Europe” industrial-policy turn could harden into de facto local-content rules that shut British firms out of subsidized value chains, precisely in sectors where production is currently split across the Channel and depends on dense, just-in-time supplier networks.
The concern is not only about headline tariffs or customs checks, but about eligibility: if EU grants, tax credits, procurement preferences, or strategic finance are conditioned on “EU-made” components, then UK plants and UK-based tier suppliers can become the weak link in an otherwise integrated European manufacturing footprint.
Uranium market tightens as utilities eye $100 long-term contracts
The uranium market is moving from a long period of episodic tightness into something closer to a structural squeeze, and the combination of higher nuclear generation, new reactor buildout, and geopolitically constrained supply is setting up the conditions for a price re-rating in 2026.
U.S. industry spot indicators ended 2025 around $82 per pound, roughly 12% higher than a year earlier, and market participants are increasingly focused on the gap between the relatively restrained spot move and the much more aggressive rally already priced into uranium equities and nuclear-fuel supply chain names.
Pentagon to stockpile $500 million cobalt in allied supply push
The Pentagon’s move to secure up to $500 million worth of cobalt over the next five years underscores how U.S. national security and industrial policy are now converging around critical minerals in a way not seen since the Cold War. Cobalt is an especially telling case: the U.S. is heavily import-dependent, China dominates refining capacity, and demand is set to surge from both defense and energy transition needs.
The Defense Logistics Agency (DLA) tender specifies alloy-grade cobalt, the form required for nickel superalloys used in jet engines and gas turbines, applications that are core to U.S. defense capabilities and aerospace leadership. That focus highlights a dual-use rationale: cobalt is not only central to civilian battery production, but also vital to high-temperature defense technologies that cannot tolerate substitutes without performance sacrifices.